

We'll always default to using a credit card (and earning more points) whenever possible, and you should too … but even in 2026, there are some things that you can't buy with plastic (or increasingly, metal). That's especially true when traveling abroad, where credit cards might not be accepted.
There's an easy solution – and it doesn't involve taking out a ton of foreign currency at home or paying a ransom to exchange money at the airport. Several major banks and flashy new fintech companies now offer debit cards that reimburse both ATM and foreign conversion fees when making cash withdrawals at ATM machines anywhere in the world. That's the best way to get money abroad, ensuring you get a fair exchange rate when turning your own U.S. dollars into whatever local currency you need.
But picking the right debit card for your international travels might be easier said than done, so we've rounded up the three best options to help you decide which is the right choice for you.
Let me be clear: We don't make a dime promoting these debit cards and checking products. We just believe they're the best options for withdrawing your money (without nasty fees) while traveling abroad.
Debit Cards vs Credit Cards
This might seem kind of elementary, but it's important to clarify exactly what a debit card is – and how that compares to a credit card. Considering most people probably already have one of these in their wallet, it's not a brand-new concept, but it may not be something you think about very often.
We spend a lot of time talking about cards on this site, and how they can help you travel more for less – but most of the time, the cards we're referring to are credit cards. You make a purchase on credit or borrow money from the issuing bank, with the promise to pay it back. In return, you're often rewarded with points, miles, or cash back to incentivize your use of the card.
With a debit card, you're using your own money for purchases. Debit cards are linked directly to a checking account – instead of writing a paper check for your purchase, you use your debit card as a form of payment. When doing so, you're electronically transferring funds from your bank account to the account of whichever merchant you made your purchase from.
Critically, you can also use debit cards to withdraw cash from your attached checking account. This feature is what makes them such a necessary travel tool for anyone heading abroad.
But outside of that, you really shouldn't be swiping your debit card to make purchases abroad. If your card is compromised, you'll assume the liability of any lost cash in your checking account until the bank can investigate the situation and reimburse you, which could take weeks.
With credit cards, you won't assume any liability in the event your card is compromised. Just make sure you have a card that waives foreign transaction fees.
Charles Schwab Investor Checking
For years, we have declared the Charles Schwab debit card as the best for international travel. That hasn't changed.
There are other contenders out there that might be better for some travelers, but it's impossible to beat the Schwab debit card's lack of fees, account minimums, and overall customer experience.
With the Schwab debit card, you can take out cash from any ATM anywhere in the world, and you'll get refunded 100% of any withdrawal or ATM fees you pay. It's a foolproof way to avoid international ATM fees and get the best possible currency exchange rate.
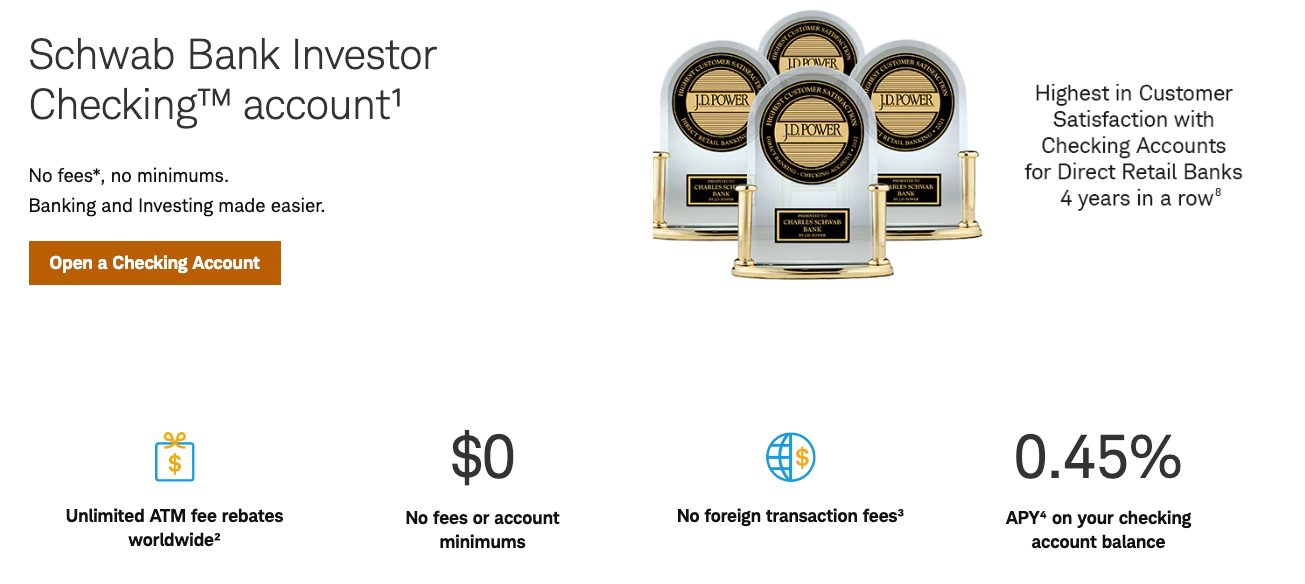
To get the debit card, you'll need to open a Charles Schwab Investor checking account as well as a linked brokerage account – typically used for investing money. This brokerage account is opened automatically when you open a Schwab checking account, but don't worry: The brokerage account is also free and has no minimum deposit or fees. Really, you don't even have to use it.
Nearly everyone on the Thrifty Traveler team uses the Charles Schwab debit card for our international travels, and we all swear by it. After years, we've never run into issues. Many of us treat our Schwab checking accounts as dedicated travel accounts, simply depositing some cash ahead of each international trip to withdraw while abroad.
Here's what you need to know about the Schwab debit card:
- Unlimited fee rebates from any ATM worldwide
- No minimum balance or monthly fees
- No foreign transaction fees on debit card purchases or ATM withdrawals
- Free Standard Checks and Visa debit card
- Charles Schwab's mobile app allows you to deposit checks with your phone
Read our full review of the Charles Schwab debit card
Learn more about the Charles Schwab High Yield Investor Checking Account & Debit Card (for full disclosure, this is not an affiliate link).
Betterment Checking
Betterment is a relative newcomer in the financial services industry, offering digital investing, retirement, and cash management services, including a mobile-first checking account with a Visa debit card.
Similar to the Charles Schwab Investor checking account, Betterment also reimburses unlimited ATM fees and doesn't pass along foreign currency conversion fees, making it an excellent choice for travelers. The lack of a minimum balance requirement also makes it a perfect option for a dedicated travel account. Simply deposit funds before your trip, and you're all set to withdraw when you get to your destination!
Here's what you need to know about the Betterment debit card:
- Unlimited fee rebates from any ATM worldwide
- No minimum balance or monthly fees
- No foreign transaction fees on debit card purchases or ATM withdrawals
- No overdraft fees
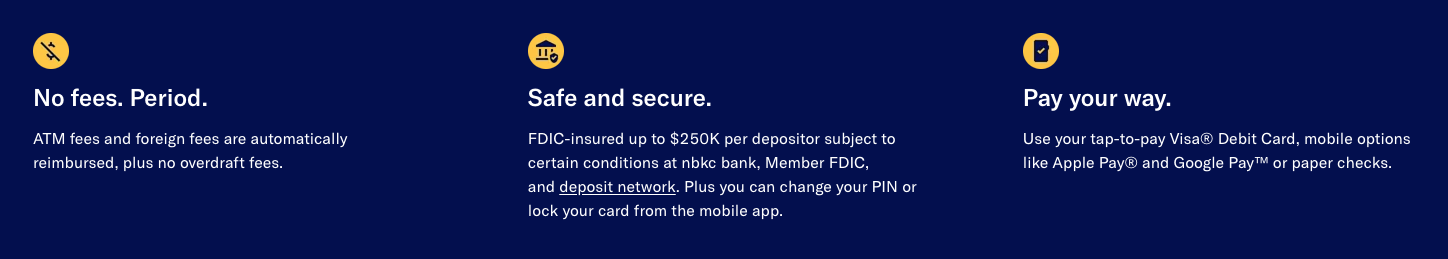
But unlike the checking account from Charles Schwab, you don't need to have a linked brokerage account with Betterment. For those who invest elsewhere or don't ever plan to use the Schwab brokerage account, opening a checking account with Betterment may be a better option.
The only real downside of Betterment is that it's a relatively young company compared to its competitors, so it's tough to say whether it'll be able to provide the same features and benefits for years to come.
Learn more about the Betterment checking account (for full disclosure, this is not an affiliate link).
Fidelity Cash Management
Fidelity is another long-standing financial institution offering a variety of financial services, ranging from cryptocurrency trading to life insurance. One of the products they offer is a cash management account with an accompanying Visa debit card.
Unlike the Betterment checking account or Schwab Investor checking account, the Fidelity Cash Management account is solely a brokerage account. So while you won't be getting two separate accounts as you would with Schwab, you'll open a brokerage account to get a Fidelity Visa debit card.
Fidelity reimburses you for all ATM fees worldwide, making it a great option for international travel. And while Charles Schwab reimburses ATM fees at the end of each statement period, Fidelity will reimburse you on the same day the fee is debited. If getting your money back as soon as possible is a priority, it's worth looking into opening a Fidelity Cash Management account.
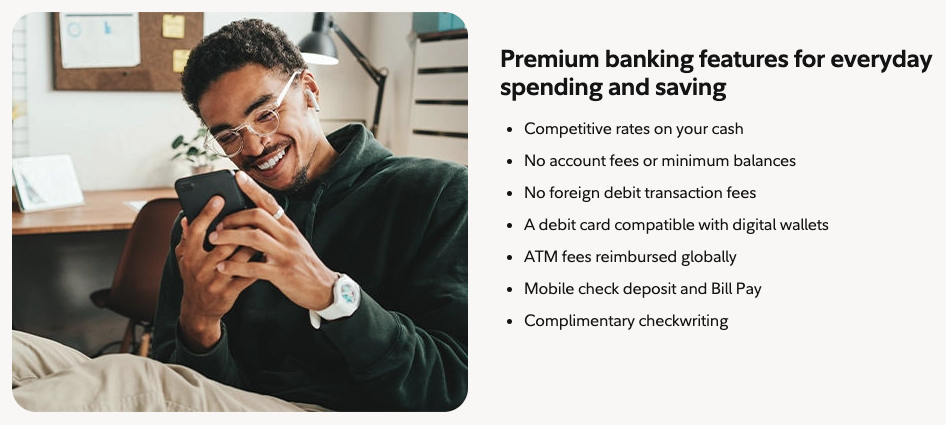
Here's what you need to know about the Fidelity debit card:
- Unlimited fee rebates from any ATM worldwide
- No account fees or minimum balance requirements
- Competitive Annual Percentage Yield (APY) on cash balances
- No foreign conversion fee on debit card purchases or ATM withdrawals
As you can see, similar to Charles Schwab or Betterment accounts, Fidelity is another strong choice. The only real downside (if you can even call it that) with Fidelity is the fact that you're opening a brokerage account instead of a checking account. I don't have a big issue with this, but I understand it could be a potential hangup for some.
Still, if you already have investment accounts with Fidelity or just want to go with a financial institution with decades of experience, this is a great option for many travelers.
Learn more about the Fidelity Cash Management account (for full disclosure, this is not an affiliate link).
Bottom Line
Whether you're paying for a taxi, tipping the bellhop, buying a snack, or something else, having some local currency on hand is often critical when traveling abroad. To do that wisely, you need the right international travel debit card.
While most debit cards will work for withdrawing cash abroad, only a select few will reimburse you for any third-party ATM fees and waive foreign conversion fees as well. Having one of these debit cards in your wallet before your next trip will save you time accessing your cash and, more importantly, help you avoid unnecessary fees along the way.
I’ve had the Schwab debit card for years and used Capital One as a backup. When Capital One switched their debit card to Discover (useless) I got the Fidelity Cash Management debit card instead since they had removed the 1% fee. I mostly use the Fidelity card as I sometimes have trouble with the Schwab card working at some ATMs – don’t know why.
I will say that mobile check deposits to my Schwab account clear within an hour with no hold so I often do that instead of transferring funds in. I don’t know why that is but I appreciate it. Both Schwab and Fidelity put long holds on funds when transfers are initiated by them. When you initiate a transfer at another institution to either of them no hold is placed on the funds when they arrive.
I’ve used Charles Schwab, Betterment, and MS/E-trade max-rate internationally. CS doesn’t reimburse foreign currency conversion fees (found that out in Taiwan). Betterment declined ATM withdraw from certain bank (didn’t allow withdraw from CIBC in Richmond, CA, and their customer service doesn’t know why). No issue with MS/E-trade max-rate so far.
My boring Ally free checking account never charges ATM fees, at home or abroad. No foreign transaction fees, no balance minimum fees, no overdraft fees.
The Morgan Stanley / E*Trade Max-Rate Checking is go-to travel debit. I moved to it from Schwab. The offers all the same features as Schwab but money transfers much quicker and it ties in well with those with the Morgan Stanley Platinum. Definitely think it should be included in the list.
2nd vote for MS/E-trade max rate debit card. I’ve used Charles Schwab, Betterment, and MS/E-trade max-rate domestic and internationally. MS/e-trade max rate is my go-to debit card now.
Finally, content worth reading. It’s always nice to find posts like this one.
I have a fidelity cash management account that acts as a checking account. you can either put your money into fdic insured banks or money market. you do not need to open a brokerage account
Since nearly everywhere we’ve travelled to seems way ahead of US in terms of CC acceptance and technology. We find we hardly ever need to use any cash so paying a small fee for one withdrawal of cash or the odd occasion when we need cash is unimportant. Is there anyone who travels who doesn’t already have a no fee, no exchange rate charge CC?
As an aside I understand (from Frank Abagnale) that you can ask your bank to make your debit card just work for withdrawing cash from ATMs and not as a card to make purchases with so making it a lot more secure from unauthorised use.
fidelity no longer charges 1% fee
Thanks for letting us know! I hadn’t caught that change.
I think this line should be more highlighted on the Fidelity Debit Card: “1% foreign conversion fee on debit card purchases and some cash withdrawals”
This is really bad and I got hit by this 1% fee while withdrawing money abroad. I’d go with Schwab until Fidelity fixes that major problem w/ their card. If Schwab can do, why Fidelity can’t have a card with no fee whatsoever?
Hi, this is an excellent guide, thanks so much! All the info in one place saves going to each website and going through complex financial info that appears so scary! As you cover the bank’s side of the fees, perhaps I also want to add some tip on the ATM side of the fees also and how to save it. Ive landed up using the mobile app – ATM Fee Saver – it helps find the fee-free or lower fee ATMs in many countries, and gives withdrawal limits too in some 30-40 countries! also gives withdrawal limits and helps calculate fees for my amount that I want to withdraw! i used it many times and saved a bunch on fees!! maybe you can create a guide on how to avoid ATM fees abroad and add this to the list, will definitely help many travellers like me!
@Michael Littman
My recommendation is to opt for 80-euro withdrawals as needed, which will dispense four 20-euro notes, unless the ATM charges a withdrawal fee that you can’t get reimbursed with your FTF-free debit card.
I love the French flea markets to find antiques at a great price. These vendors are not regular sellers , they are just cleaning out their attic so they require cash in small bills like 5 euro and 10 euro bills. I recommend ordering small denomination currency from your bank before going to Europe since these denominations are not offered in ATMs . If the ATM offers you a choice , select the smallest size like 20 euro rather than 50 euros.
Thanks for the article. I went with Betterment. I was needing something else to help with international travel money other than credit cards.
It’s better to refresh our insight after reading your article.
I might jump to Betterment after reading your article. While CS will reimburse ATM fees they don’t reimburse currency conversion fees. So glad to learn about Betterment will not pass any currency conversion fees.